Key takeaways:
- Every 2026 return asks whether you received or disposed of a digital asset, and selling, swapping, spending crypto or earning rewards all mean Yes.
- Sales go on Form 8949 under boxes G to L, then Schedule D. Because 2026 is the first year brokers report basis for coins bought after 2025, many exchange sales can skip Form 8949 and go straight onto Schedule D line 1a or 8a, while staking rewards and other crypto income belong on Schedule 1 line 8v.
- In our worked return, $17,629 of crypto gains and staking income added about $2,130 of tax.
Crypto touches more of a tax return than most people expect. There’s a Yes or No question on the first page, a form for every sale, a schedule that totals them, and a separate line for anything you earned in crypto. Each of those has its own rules on what counts.
This guide shows how to report crypto on taxes for tax year 2026, the return due on April 15, 2027. Line numbers and box labels come from the IRS’s 2026 draft forms. The rules are quoted from the 2025 instructions, the latest the IRS had published when we checked on November 11, 2026, so expect small changes when the final 2026 versions arrive in early 2027.
Step 1: Answer the digital asset question
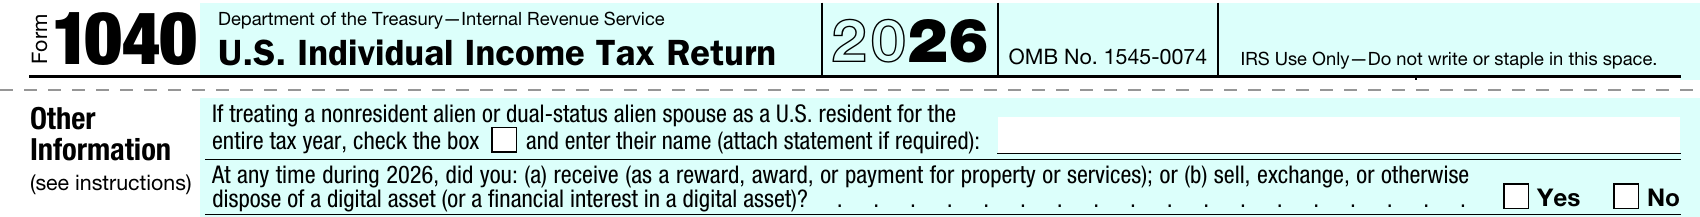
Page 1 of Form 1040 asks: “At any time during 2026, did you: (a) receive (as a reward, award, or payment for property or services); or (b) sell, exchange, or otherwise dispose of a digital asset (or a financial interest in a digital asset)?” It’s the first thing on any crypto tax return, and you can’t skip it. The instructions say you must answer “whether or not you received a Form 1099-DA.”
Here’s how the question appears on the IRS’s 2026 draft of Form 1040, below the filing status boxes.
The table sorts the common cases using the IRS’s own lists from the Form 1040 instructions and its digital assets page.
| What you did in 2026 | Answer |
|---|---|
| Sold crypto for dollars | Yes |
| Swapped one coin for another | Yes |
| Paid for something with crypto | Yes |
| Received staking, mining or airdrop rewards | Yes |
| Got paid in crypto for work | Yes |
| Moved crypto between your own wallets and paid the network fee in crypto | Yes |
| Only held crypto | No |
| Bought crypto with dollars, including through PayPal or Venmo | No |
| Moved crypto between your own wallets with no crypto fee | No |
The fee row surprises people. The instructions say an own-wallet transfer “alone” is a No, but the IRS’s digital assets page adds an exception: if you paid the transaction fee in crypto, “This would be a digital asset transaction.” Spending a little ETH on gas counts as a disposal of that ETH.
Plenty of filers get this box wrong. A 2024 TIGTA audit counted 2,427,446 returns for tax years 2020 to 2022 that checked both Yes and No, or neither. Answering Yes doesn’t mean you owe anything, though. It just tells the IRS to expect the forms that follow.
Step 2: Sort each transaction into income, a disposal or neither
Most of how to report crypto on taxes comes down to sorting. The IRS treats crypto as property, not currency, so every event lands in one of three groups: income you received, a disposal that creates a gain or loss, or something that isn’t taxable at all.
Income is taxed at your ordinary rates on its dollar value when it arrives. A disposal is taxed on the gap between what you got and what you paid. Some events are both. Get paid 0.1 BTC for freelance work and that’s income now; sell the 0.1 BTC later and the sale is a separate disposal, measured from the value you reported as income.
Buying, holding and moving coins between your own wallets don’t go on the return as transactions. You still need the records, because the purchase sets the basis you’ll use when you eventually sell.
Step 3: Work out basis and holding period
Your basis is what a coin cost you, and the Form 8949 instructions spell out that it includes “transaction fees, commissions, transfer taxes, and other acquisition costs.” Buy 10 coins for $20,000 and pay a $100 fee, and each coin’s basis is $2,010, not $2,000.
The holding period decides the tax rate. Under the instructions you “begin counting on the day after you received the property and include the day you disposed of it.” Held for more than a year, the gain is long-term and taxed at 0%, 15% or 20%. Held a year or less, it’s short-term and taxed like wages.
Since January 1, 2025, basis is tracked wallet by wallet. Rev. Proc. 2024-28 applies the identification rules “to units held within a single wallet or account”, which ended the old habit of pooling every wallet into one set of lots.
Inside a self-custody wallet, the regulation (26 CFR 1.1012-1(j)) uses first in, first out unless you record which units you’re selling before the sale. It also says “the date any units were transferred into the taxpayer’s wallet is disregarded”, so coins keep their original purchase date when you move them.
At an exchange, you pick units by telling the broker before the sale or with a standing order. Under Notice 2025-7, extended by Notice 2026-20, you can instead record your choice in your own books, but that relief ends on December 31, 2026. From 2027, specific identification at a broker has to go through the broker.
Step 4: Report sales on Form 8949 and Schedule D
Form 8949 lists each disposal, with what you sold, when you bought and sold it, the proceeds, the basis and the result. On Form 8949, crypto has its own boxes, and the instructions say plainly not to use boxes C or F for it.
| Box | Holding period | When to use it |
|---|---|---|
| G | Short-term | Form 1099-DA shows basis was reported to the IRS |
| H | Short-term | Form 1099-DA shows basis was not reported to the IRS |
| I | Short-term | No Form 1099-DA, for example a self-custody wallet |
| J | Long-term | Form 1099-DA shows basis was reported to the IRS |
| K | Long-term | Form 1099-DA shows basis was not reported to the IRS |
| L | Long-term | No Form 1099-DA |
Box 2 on Form 1099-DA tells you which row applies, and our Form 1099-DA guide goes through every box on the broker’s form. For coins bought before 2026 or moved onto the exchange from elsewhere, the broker usually won’t report basis, so you fill it in yourself under box H or K.
There’s a shortcut worth knowing. If your 1099-DA shows basis reported to the IRS and you need no adjustments, you can skip Form 8949 for those sales and enter the totals straight on Schedule D line 1a (short-term) or 8a (long-term). That only became broadly useful for crypto in 2026, when brokers began reporting basis for coins bought after 2025.
Schedule D adds everything up. Line 7 is your net short-term result, line 15 your net long-term result, and line 16 combines them and goes to Form 1040 line 7a. If the total is a loss, you can deduct up to $3,000 of it a year ($1,500 if married filing separately) and carry the rest forward to later years.
One rule from stocks mostly doesn’t apply. The Schedule D instructions say wash sale rules “generally apply to transactions involving digital assets that are also stock or securities for tax purposes (tokenized securities)”, which leaves ordinary coins outside that wording.
Step 5: Report crypto you earned as income
Rewards and payments go elsewhere. Schedule 1 has a line for them, line 8v, “Digital assets received as ordinary income not reported elsewhere”, and the instructions name “income from forks, staking, or mining” as examples. The total flows through Schedule 1 line 10 to Form 1040 line 8.
Staking rewards are taxable once you can use them. Rev. Rul. 2023-14 taxes their fair market value in the year you gain “dominion and control”, whether you stake on your own or through an exchange. In June 2026 the Tax Court reached the same result on its own reasoning in Paschall (T.C. Memo. 2026-46): a couple owed tax on $33,354 of Cardano staking rewards from eToro for 2021, even though they didn’t sell them that year.
That case has a second lesson. eToro’s Form 1099-MISC went to the couple’s old address, and they found out only when the IRS sent a CP2000 notice in November 2023. The IRS’s position is that you report all crypto income “regardless of the amount or whether you receive a payee statement.”
If crypto is part of a business, it goes on Schedule C instead. The IRS’s virtual currency FAQ says crypto received as an independent contractor “constitutes self-employment income and is subject to the self-employment tax”, and Schedule SE applies once net earnings reach $400. A shop that takes stablecoin payments reports those sales as business income at their dollar value. Wages paid in crypto are reported like any other pay, on Form 1040 line 1a.
How to report crypto on taxes: one 2026 return, start to finish
The clearest way to see how to report crypto on taxes is one complete return. Dana is single, earns $60,000 in wages, takes the standard deduction and has no losses carried over. The coin names are placeholders and the prices are made up, but every rule and rate comes from the IRS sources above.
| Date | What Dana did | Where |
|---|---|---|
| March 4, 2024 | Bought 1 Coin A for $30,000, fees included | Exchange |
| February 2, 2026 | Bought 10 Coin B at $2,000 each plus a $100 fee | Exchange |
| March 10, 2026 | Moved 2 Coin B to her own wallet, no fee, and staked them | Own wallets |
| April 30 and August 31, 2026 | Staking rewards of 0.1 Coin B at $2,100, then 0.1 at $2,300 | Own wallet |
| June 10, 2026 | Sold the Coin A for $45,000, less a $45 fee | Exchange |
| September 15, 2026 | Sold 4 Coin B for $10,000, less a $20 fee | Exchange |
| November 20, 2026 | Paid for a $1,500 laptop with 0.6 Coin B | Own wallet |
The transfer isn’t taxable, and the two coins keep their February purchase date and their $2,010 basis. Everything else lands on a form.
The three disposals
The Coin A sale is long-term: bought in March 2024, sold in June 2026. The proceeds are $44,955 after the fee, and the basis is $30,000, for a $14,955 gain. Coin A was bought before 2026, so the 1099-DA won’t show its basis as reported to the IRS. It goes on Form 8949 under box K, then Schedule D line 9.
The Coin B sale is short-term. Proceeds are $9,980, basis is 4 × $2,010 = $8,040, and the gain is $1,940. These coins were bought in 2026 at the same exchange, so they’re covered and the 1099-DA reports the basis. With no adjustments, Dana can enter this sale directly on Schedule D line 1a.
The laptop counts as a sale too. The IRS measures it by the value of what you got, so the proceeds are $1,500. With no identification recorded, first in, first out applies inside her wallet, which means the 0.6 coins come from the February lot at $2,010 each, a $1,206 basis and a $294 short-term gain. No broker was involved, so it goes under box I and then Schedule D line 3.
Staking income and the totals
The rewards are income at their value on each date: $210 plus $230, or $440. That’s Schedule 1 line 8v, and it reaches Form 1040 line 8.
The totals then travel from Schedule D and Schedule 1 to these lines of the 2026 draft Form 1040.
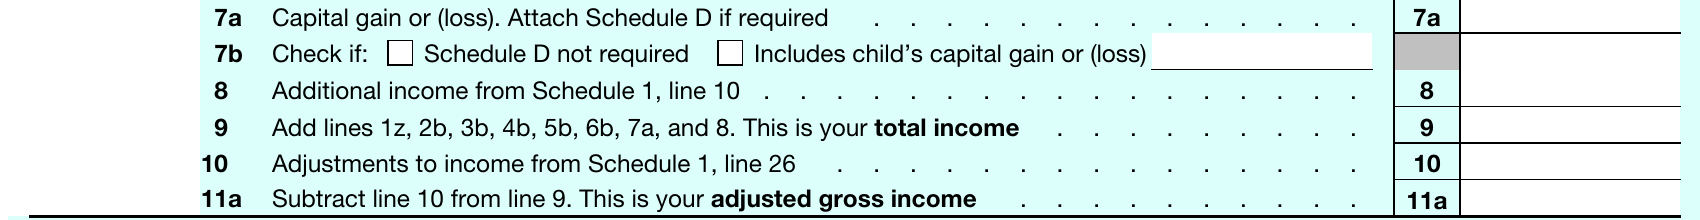
Here are Dana’s figures for each of those lines and the Schedule D lines behind them.
| Line | Form | Amount |
|---|---|---|
| 1a | Schedule D, covered short-term sale | $1,940 |
| 3 | Schedule D, box I sale | $294 |
| 7 | Schedule D, net short-term | $2,234 |
| 9 and 15 | Schedule D, box K sale and net long-term | $14,955 |
| 16 | Schedule D, total, carried to Form 1040 line 7a | $17,189 |
| 8 | Form 1040, from Schedule 1 line 8v | $440 |
| 9 and 11a | Form 1040, total income and adjusted gross income | $77,629 |
| 12e | Form 1040, standard deduction for a single filer | $16,100 |
| 15 | Form 1040, taxable income | $61,529 |
She checks Yes on the digital asset question, since she sold, earned rewards and spent crypto.
The tax
Long-term gains get their own rates. For 2026, Rev. Proc. 2025-32 sets the 0% band for single filers up to $49,450 of taxable income and the 15% band up to $545,500. Dana’s ordinary income, wages plus short-term gains and staking minus the deduction, comes to $46,574.
That leaves $2,876 of room under $49,450, so $2,876 of the long-term gain is taxed at 0% and the other $12,079 at 15%, or $1,811.85. Tax on the $46,574 from the 2026 draft tax table is $5,341. The total is $7,153.
Taxing all $61,529 as ordinary income would have cost $8,248, so the long-term rates saved her $1,095. Without any crypto her taxable income would be $43,900, and the 2026 rate schedule puts the tax on that at about $5,023, so the crypto added roughly $2,130 to her bill.
We built this calculation on the 2025 Qualified Dividends and Capital Gain Tax Worksheet with the 2026 amounts, because the 2026 version isn’t out yet. Two other taxes don’t apply to her: the 3.8% net investment income tax starts at $200,000 of income for a single filer, and she has no business, so no self-employment tax.
Mistakes to check before you file
A few errors turn up on crypto tax returns again and again, and some are still repeated in guides online. Run through these before you submit.
- Reporting exchange sales under box C or F. Since 2025 the Form 8949 crypto boxes are G to L.
- Expecting a Form 1099-B from your exchange. Brokers report crypto sales on Form 1099-DA.
- Accepting a blank or zero basis on a 1099-DA. If box 2 isn’t checked, the basis is yours to supply, and leaving it out makes the whole sale look like profit.
- Skipping staking rewards because no form arrived. Self-custody rewards never generate a form, and they’re taxable anyway.
- Forgetting crypto spent on purchases or gas. Each payment is a small disposal with its own gain or loss.
If an IRS notice does arrive, answer it within its deadline. One Reddit user described on r/CryptoTax how a CP2000 listed every 2021 trade without basis and claimed $12,000 of tax; by the time the corrections went in, the IRS said the reply had come too late. That’s one person’s account, but the mechanism is the same one behind mistake 3.
Frequently asked questions
Do I have to report crypto if I didn’t sell any?
You still answer the digital asset question, and you answer No if all you did was buy with dollars, hold, and move coins between your own wallets without paying fees in crypto. If you earned staking rewards, got paid in crypto or spent any, you answer Yes and report that activity even without a sale.
What if I didn’t get a Form 1099-DA?
Report the transactions on your crypto tax return anyway. Sales with no broker form go on Form 8949 under box I (short-term) or box L (long-term), using your own records for dates, proceeds and basis. The IRS says income and gains are reportable whether or not you receive a form.
How do I report crypto losses?
They go on Form 8949 and Schedule D like gains. Losses first offset gains, and up to $3,000 of any net loss ($1,500 if married filing separately) reduces your other income for the year. The rest carries forward to later years.
Are staking rewards taxable if I never sold them?
Yes. Under Rev. Rul. 2023-14 they’re income at their fair market value when you gain control of them, and in 2026 the Tax Court taxed rewards a couple hadn’t sold. Report them on Schedule 1 line 8v unless they’re part of a business.
When is the 2026 tax return due?
April 15, 2027, for most people. Filing Form 4868 gives an automatic six-month extension of time to file, to October 15, 2027, but the IRS still expects any tax due to be paid by April 15.